4% of the exam · 9 free questions

    Florida Types of Mortgages and Financing Practice Questions and Answers

    Follow a mortgage from origination to the secondary market, then compare how different loans work. Try 9 free scored questions, explanations of every choice, six worked examples, and a discount-points calculator. No account needed.

    Rules in effect through . Reviewed . Review and sources

    Start the 9-question quiz

    Full exam prep in Pass Florida. Free to start.

    Open the web appDownload the app

    Quiz mode · Test yourself

    Types of Mortgages and Financing Practice Questions

    9 practice questions on types of mortgages and financing, scored, each with a full explanation after you answer. Every question is also written out below if you would rather study at your own pace.

    9 questions
    ~7 min
    4% of the exam

    All 9 questions and explanations are free. This area carries 4% of the published sales associate exam outline, about 4 questions. The short quiz samples the topic; its score does not predict your state-exam result.

    01 / Recognize the structure

    Six financing arrangements worth keeping separate

    Look at what secures the loan, when money is advanced, and how the debt is repaid. Similar names can describe very different arrangements.

    Multiple parcels

    Blanket mortgage

    One mortgage covers more than one parcel. A partial release clause states how a specified parcel can be released from that lien after the agreed conditions are met.

    Watch for: A release from this mortgage does not remove every other lien on the property.
    Real and personal property

    Package mortgage

    Financing includes the real estate and personal property, such as separately identified movable furnishings. The clue is the mix of property types, not the number of lots.

    Watch for: An attached item may be a fixture. The question should identify the personal property clearly.

    Money released in draws

    Construction loan

    Funds are advanced as work progresses under the loan agreement. A short-term construction loan may be repaid with permanent takeout financing. A construction-to-permanent arrangement may convert under its agreed terms.

    Watch for: The stated maturity and conversion terms control. Completion does not make every construction loan mature in exactly the same way.

    Seller takes back financing

    Purchase-money mortgage

    In the syllabus's seller-financing example, the buyer gives the seller a mortgage for part of the purchase price. More broadly, purchase-money financing refers to financing used to acquire the property.

    Watch for: A seller-held purchase-money mortgage need not be a wraparound. Look for an underlying loan that remains in place.

    Loan labels can overlap. A mortgage may be conventional, fixed-rate, and fully amortizing at the same time. Compare rate and repayment terms below.

    02 / Trace one common path

    From a borrower's loan to the secondary market

    The primary market creates the mortgage. The secondary market trades existing loans and mortgage-backed securities, helping funds circulate back into lending.

    1. Primary market

      Lender makes the loan

      The borrower signs loan documents and receives financing from the originating lender.

    2. Secondary market

      Existing mortgage is sold

      A purchaser acquires the eligible loan. The lender can use the sale proceeds to fund more loans.

    3. Securitization

      Investors buy MBS

      Loans are pooled into mortgage-backed securities. Investors receive payments under the securities' terms.

    Loan ownership and servicing are different.

    The servicer handles payments and other loan administration. It may continue servicing after the loan is sold, or servicing may transfer too. A sale does not by itself change the signed loan terms. Follow the applicable transfer notice for payment instructions.

    Not every mortgage follows all three steps: a lender may retain a loan in its portfolio.

    Fannie Mae

    Federal National Mortgage Association

    Buys eligible mortgages from lenders and packages many into MBS that it guarantees.

    It does not originate home loans directly to consumers. Its purchases can replenish a lender's funds.

    Freddie Mac

    Federal Home Loan Mortgage Corporation

    Buys eligible residential mortgages and packages most into securities sold to investors.

    It also supports secondary-market liquidity. Do not treat it as a retail lender simply because its name includes “Home Loan.”

    Ginnie Mae

    Government National Mortgage Association

    Guarantees timely principal and interest on qualifying MBS issued by approved issuers and backed by federally insured or guaranteed loans.

    It is a government corporation within HUD. It does not buy the mortgages or issue the MBS itself. Its MBS guaranty carries the full faith and credit of the United States.

    Fannie Mae and Freddie Mac are government-sponsored enterprises. Ginnie Mae is a government corporation. FHA loan insurance and Ginnie Mae's MBS guaranty protect different parts of the financing chain. Work through the four roles in an example.

    03 / Turn a percentage into dollars

    Discount points: cost first, savings second

    One point costs 1% of the loan amount. That defines its dollar cost, not a guaranteed reduction in the interest rate.

    Try your own numbers

    What do the points cost?

    Use the amount borrowed and the monthly principal-and-interest savings quoted for two otherwise comparable offers. Points do not imply a fixed rate reduction.

    Your calculation

    $4,500.00

    Upfront discount points

    $300,000.00 × 1.5% = $4,500.00

    About 60 months to break even

    $4,500.00 ÷ $75.00 in monthly savings. Rounded up to the next whole monthly payment.

    This is a simple cash-flow exercise with constant savings. It excludes other fees, tax effects, loan-balance differences, and the time value of money. It does not calculate APR or recommend a loan. Compare the expected time you will keep the loan with the break-even period.

    Discount points

    Pay more at closing for a lower interest rate relative to comparable zero-point pricing. The rate reduction depends on the lender, loan, and market.

    Origination fee

    A charge for originating the loan. A fee expressed as a percentage does not automatically purchase a lower rate.

    Lender credit

    A credit can reduce upfront closing costs in exchange for higher-rate pricing. Some credits have other purposes, so read the offer's terms.

    CFPB: discount points and lender credits explains these tradeoffs. Try the scored points calculation.

    Does one point always lower the rate by 0.25% or raise yield by 0.125%?

    No. There is no universal conversion from a discount point to a particular mortgage rate reduction. The course's approximate-yield exercises are separate from pricing a real loan. If a question supplies a rule of thumb, use it only for that exercise.

    A loan's actual yield depends on its cash flows and payoff timing. Do not label an approximation as APR or use it as a guaranteed lender quote.

    CFPB: discount points and lender credits · FREC Course I syllabus: Sections 12 and 13

    04 / Separate the benefit from the obligations

    HECM: a loan against equity, with conditions

    The FHA-insured Home Equity Conversion Mortgage has specific eligibility and occupancy rules. It is not a grant, and the lender does not simply take ownership when the loan begins.

    Eligibility

    62 or older is one requirement

    Meet the principal-residence, equity, financial, property, and HUD-approved counseling requirements. Any existing mortgage must be paid off at HECM closing, using available proceeds or other funds.

    CFPB: HECM age, equity, and counseling requirements

    Ongoing costs

    No required monthly P&I is not no bills

    Pay taxes, insurance, and other required property charges, maintain the home, and meet occupancy rules. The balance can grow as interest and charges accrue. Failure to satisfy loan conditions can make the loan due and lead to foreclosure.

    CFPB: reverse mortgage borrower responsibilities

    After a borrower's death

    A spouse's status matters

    A co-borrower differs from a non-borrowing spouse. An eligible non-borrowing spouse may qualify for repayment deferral under HUD's conditions, but does not receive further loan advances. Other occupants do not automatically receive that protection.

    CFPB: HECM co-borrowers and eligible non-borrowing spouses

    The age-62 statement concerns the FHA HECM program. Do not assume every proprietary reverse mortgage has identical requirements. HUD: FHA Home Equity Conversion Mortgages · Try the HECM question.

    05 / Work through the facts

    Six examples that go beyond a definition

    Try each answer before opening the explanation. All dollar amounts and rates here are teaching examples, not current loan offers.

    Worked example 01

    Release one lot, not the entire blanket

    A developer owes $900,000 under a blanket mortgage. Its partial release clause requires $75,000 applied to principal to release one specified lot. What balance remains after that payment? Ignore interest and fees.

    Show the answer and reasoning

    $825,000 remains secured by the unreleased parcels.

    Subtract the contract's release payment: $900,000 − $75,000 = $825,000. The released lot leaves this mortgage's collateral. Do not divide the balance equally among the lots unless the clause says to do that. Other liens require their own review.

    Worked example 02

    Two points and a separate origination fee

    A $320,000 loan has 2 discount points and a separate 0.5% origination fee. What are these two charges together?

    Show the answer and reasoning

    $8,000: $6,400 in points plus $1,600 in origination fees.

    Use the loan amount for both stated percentages. $320,000 × 0.02 = $6,400; $320,000 × 0.005 = $1,600. The origination fee does not automatically buy a lower rate. These two charges are not the borrower's entire cash to close.

    Worked example 03

    When do monthly savings recover the points?

    For two otherwise comparable fixed-rate loan offers, $4,500 in extra upfront points saves $75 a month in principal and interest. Using only those cash flows, how long is the simple break-even period?

    Show the answer and reasoning

    60 months, or 5 years: $4,500 ÷ $75.

    After 48 monthly savings of $75, only $3,600 has been recovered. This shortcut assumes constant savings and ignores the time value of money, tax effects, and differences in loan balances. It is a comparison exercise, not a complete borrowing decision.

    Worked example 04

    Apply the ARM cap after index plus margin

    At an ARM's first adjustment, the index is 5% and the margin is 2.25%. Its initial rate was 4.5%, the first-adjustment increase cap is 2 percentage points, and the lifetime ceiling is 9.5%. Assume no other limits or rounding. What rate applies?

    Show the answer and reasoning

    6.5%. The 7.25% fully indexed rate is limited by the first-adjustment cap.

    Index plus margin is 5% + 2.25% = 7.25%. The first adjustment can rise only to 4.5% + 2% = 6.5%, which is also below the lifetime ceiling. A two-percentage-point cap is not a 2% multiplication of the old rate.

    Worked example 05

    Split a payment into interest and principal

    A loan has a $240,000 principal balance, a 6% annual interest rate, and a $1,500 monthly principal-and-interest payment. Using annual rate divided by 12, how much of this payment reduces principal?

    Show the answer and reasoning

    $300 goes to principal; the new balance is $239,700.

    This month's interest is $240,000 × 0.06 ÷ 12 = $1,200. Subtract from the $1,500 payment to get $300 of principal. With the same rate, the next month's interest is $239,700 × 0.06 ÷ 12 = $1,198.50. Escrow for taxes and insurance is separate.

    Worked example 06

    Identify what Ginnie Mae guarantees

    An approved private issuer pools eligible FHA-insured mortgages into MBS. Ginnie Mae guarantees the timely principal-and-interest payments on the securities. Did Ginnie Mae originate the loans or issue those securities?

    Show the answer and reasoning

    Neither. It provides the MBS guaranty in this example.

    Keep the layers separate: the lender originates the mortgages, FHA insures the eligible loans, the approved issuer issues the MBS, and Ginnie Mae guarantees the qualifying securities' payments. Buying mortgages is the role associated with Fannie Mae and Freddie Mac in the comparison.

    06 / Connect the remaining concepts

    Payment structures, lenders, and federal roles

    Use these notes to connect the nine scored questions with the broader course material. A short definition is useful only if you can recognize it in a transaction.

    Fixed rate, adjustable rate, and repayment structure

    A fixed interest rate does not by itself mean a loan fully amortizes. A fully amortizing loan pays off over its scheduled term through required payments. A partially amortized loan leaves a balloon balance at maturity. An interest-only period does not reduce principal through the scheduled interest payments. These features describe different parts of a loan, so a mortgage can fit more than one label.

    ARM caps versus payment caps

    An ARM uses an index and a contractual margin, subject to its adjustment rules. Initial, subsequent, and lifetime interest-rate caps can differ. A payment cap limits the payment rather than necessarily limiting interest accrual. If the required payment is less than the interest due and the unpaid interest is added to principal, the balance grows through negative amortization.

    Conventional versus conforming

    Conventional means the mortgage is not insured or guaranteed by a federal loan program such as FHA or VA. Conforming refers to meeting the applicable Fannie Mae or Freddie Mac purchase standards, including the relevant loan limit and other requirements. A loan can be conventional and nonconforming. A portfolio lender keeps loans as investments rather than selling every loan into the secondary market.

    Primary-market lenders, brokers, and servicers

    Banks, savings associations, credit unions, nonbank mortgage lenders, and sellers can supply financing. A mortgage broker generally arranges financing between a borrower and a lender; a mortgage loan originator works on the application and loan terms. Servicing means administering the loan, including payments. The company servicing a loan need not own it, and a loan sale does not by itself rewrite the signed loan terms.

    Intermediation and disintermediation

    Intermediation channels savers' funds through financial institutions to borrowers. Disintermediation describes funds moving away from those intermediaries toward other investments or direct financing channels. Reduced deposit funding can affect a lender's lending capacity, but deposits are not every lender's only source of funds. Secondary-market sales provide another way to replenish capital.

    The Fed influences mortgage rates; it does not quote them

    Federal Reserve policy influences short-term rates and broader financial conditions. Longer-term mortgage rates also reflect market yields, expected inflation, credit risk, and loan pricing. Learn open-market operations, the discount window, and reserve concepts for the exam, but keep the current framework in view: reserve requirement ratios have been zero since March 26, 2020. Modern implementation also uses administered rates, including interest on reserve balances.

    FHFA, FHA, and the Fed have different jobs

    FHFA supervises Fannie Mae, Freddie Mac, and the Federal Home Loan Bank System. FHA is part of HUD and insures eligible mortgages; it is not the Federal Housing Finance Agency. The Federal Reserve conducts monetary policy and has separate supervisory responsibilities. None of these labels means the agency simply gives every buyer a government mortgage.

    HELOC, home equity loan, and biweekly payments

    A home equity loan generally advances a lump sum; a HELOC allows borrowing up to a limit during its draw period under its terms. A true biweekly schedule of half the monthly payment every two weeks produces 26 half-payments a year, equal to 13 monthly payments. Twice-monthly payments produce only 24 halves. Check how extra payments are applied before assuming faster payoff.

    07 / Review every answer

    All 9 types of mortgages and financing questions and answers

    Open the concept you want to review. Every question, answer, wrong-choice explanation, and source is available without completing the quiz or signing in.

    Study mode · Every question explained9 questions, answer reasoning, and 27 explanations of the other choices

    Try each question before opening its answer. These are original practice items, not actual or recalled Pearson VUE exam questions.

    1. Question 1 · fin-1 · Blanket mortgages and partial releases

      A developer finances several lots under one mortgage. Its partial release clause allows a specified lot to leave the lien when the agreed release payment and other conditions are met. What is this arrangement?

      1. A package mortgage covering furnishings
      2. A blanket mortgage with a partial release clause
      3. A wraparound mortgage retaining an older loan
      4. A reverse mortgage for an owner-occupant
      Show answer and explanation

      Answer B. A blanket mortgage with a partial release clause

      A blanket mortgage covers multiple parcels. A partial release clause provides for releasing a specified parcel from that mortgage when the stated conditions are met. The release payment comes from the agreement; it is not automatically an equal fraction of the loan balance. Releasing this lien does not establish that all other title matters are clear.

      Remember: Blanket describes the multiple parcels. Partial release describes how one parcel can leave that lien.

      Why the other choices do not work
      • A. A package mortgage covering furnishings

        A package mortgage combines real and personal property, not simply several lots.

      • C. A wraparound mortgage retaining an older loan

        A wraparound includes an existing loan balance in a new, larger obligation. That is not the fact being tested.

      • D. A reverse mortgage for an owner-occupant

        A reverse mortgage concerns borrowing against home equity under its terms; it does not describe this development arrangement.

      Sources: FREC Course I syllabus: Sections 12 and 13

      Report a problem with fin-1
    2. Question 2 · fin-2 · Package mortgage collateral

      A buyer finances a condominium together with separately identified movable furniture that remains personal property. Which mortgage type describes this combined financing?

      1. A blanket mortgage
      2. A construction mortgage
      3. A reverse mortgage
      4. A package mortgage
      Show answer and explanation

      Answer D. A package mortgage

      A package mortgage includes both real and personal property. Here, the condominium is real property and the specified movable furniture is personal property. Merely including an attached fixture would not establish the same distinction because a fixture may be part of the real estate.

      Remember: Use the stated property classification. Not every appliance is automatically personal property.

      Why the other choices do not work
      • A. A blanket mortgage

        A blanket mortgage covers multiple parcels; the defining clue here is the personal property included.

      • B. A construction mortgage

        Construction financing advances funds for building work, which is not described here.

      • C. A reverse mortgage

        A reverse mortgage provides loan proceeds against eligible home equity. Age and reverse-payment conditions are not the clue in this question.

      Sources: FREC Course I syllabus: Sections 12 and 13

      Report a problem with fin-2
    3. Question 3 · fin-3 · Wraparound structure and the underlying loan

      A seller leaves an existing first mortgage in place and takes a new, larger junior obligation from the buyer that includes the old loan balance. The buyer pays the seller, who continues paying the original lender. What is this?

      1. A wraparound mortgage
      2. A blanket mortgage
      3. A refinance that pays off the original mortgage
      4. A HECM reverse mortgage
      Show answer and explanation

      Answer A. A wraparound mortgage

      The new wraparound obligation includes the unpaid underlying balance, while the original loan remains in place. The underlying due-on-sale clause must be addressed. Federal law generally permits enforcement of such clauses, subject to its exceptions and the loan terms. Keeping payments current does not itself grant permission for the transfer.

      Remember: A wraparound retains the old loan. A replacement refinance pays that loan off.

      Why the other choices do not work
      • B. A blanket mortgage

        A blanket mortgage is identified by multiple parcels under one lien, not by an underlying debt included in a new obligation.

      • C. A refinance that pays off the original mortgage

        The facts explicitly say the original mortgage remains in place.

      • D. A HECM reverse mortgage

        HECM financing has different eligibility and repayment features and is not the seller collecting on this junior obligation.

      Sources: 12 U.S.C. 1701j-3: due-on-sale clauses and exceptions · FREC Course I syllabus: Sections 12 and 13

      Report a problem with fin-3
    4. Question 4 · fin-4 · Construction draws and takeout financing

      A builder obtains a short-term loan disbursed in draws as work progresses. The contract requires repayment at completion, and the builder plans to replace it with permanent financing. What is the short-term loan?

      1. A permanent amortizing loan already in its repayment term
      2. A package mortgage solely for movable furnishings
      3. A construction loan
      4. A HECM reverse mortgage
      Show answer and explanation

      Answer C. A construction loan

      The staged advances are construction draws. In this example, the agreement requires repayment at completion, commonly using permanent takeout financing. Other construction-to-permanent arrangements can convert under their terms. Do not assume every construction loan has identical maturity or conversion provisions.

      Remember: The draws identify the construction phase. The takeout loan supplies the later permanent financing.

      Why the other choices do not work
      • A. A permanent amortizing loan already in its repayment term

        Permanent financing is the planned next step, not the draw loan described.

      • B. A package mortgage solely for movable furnishings

        A package mortgage includes both real and personal property. Draws tied to building progress point to construction financing.

      • D. A HECM reverse mortgage

        A HECM uses a different equity-conversion structure and is not this builder’s short-term project loan.

      Sources: FREC Course I syllabus: Sections 12 and 13

      Report a problem with fin-4
    5. Question 5 · fin-5 · Primary-market origination

      A lender originates a home-purchase mortgage directly with a borrower. In which market does this transaction occur?

      1. The secondary mortgage market
      2. The primary mortgage market
      3. The market for already-issued mortgage-backed securities
      4. Only the Federal Reserve discount window
      Show answer and explanation

      Answer B. The primary mortgage market

      The primary market is where the borrower obtains a newly originated loan from a lender. A later sale of that existing mortgage is secondary-market activity. The lender may instead retain the loan in its portfolio. Origination, ownership, and servicing are related but distinct roles.

      Remember: Identify what is happening in the transaction, not just the company’s name.

      Why the other choices do not work
      • A. The secondary mortgage market

        The secondary market deals with existing loans and mortgage-backed securities, rather than this original borrower loan.

      • C. The market for already-issued mortgage-backed securities

        An MBS investor transaction occurs after loans have been originated and pooled; it is not this borrower’s closing.

      • D. Only the Federal Reserve discount window

        The discount window lends to eligible depository institutions, not directly to a consumer purchasing a home.

      Sources: Fannie Mae: loan purchases and mortgage-backed securities · FREC Course I syllabus: Sections 12 and 13 · Federal Reserve: monetary policy

      Report a problem with fin-5
    6. Question 6 · fin-6 · Fannie Mae, Freddie Mac, and Ginnie Mae

      Which entity purchases eligible mortgages from lenders, helping replenish funds for new lending, rather than originating loans directly to homebuyers?

      1. Fannie Mae
      2. Ginnie Mae, acting as the purchaser of those mortgages
      3. The Florida Real Estate Commission
      4. A county property appraiser
      Show answer and explanation

      Answer A. Fannie Mae

      Fannie Mae purchases eligible loans and securitizes many of them. Freddie Mac also buys residential mortgages from lenders. Ginnie Mae supports the secondary market differently: it guarantees timely payments on qualifying MBS issued by approved issuers. Ginnie Mae does not purchase those mortgages or issue the securities itself.

      Remember: Fannie and Freddie buy loans. Ginnie supplies the guaranty on qualifying MBS.

      Why the other choices do not work
      • B. Ginnie Mae, acting as the purchaser of those mortgages

        Ginnie Mae’s role is the qualifying MBS guaranty, not purchasing the mortgages in this question.

      • C. The Florida Real Estate Commission

        FREC administers Florida real estate license regulation; it does not buy mortgages to replenish lender funds.

      • D. A county property appraiser

        A property appraiser’s tax-assessment role is unrelated to secondary-market mortgage purchases.

      Sources: Fannie Mae: loan purchases and mortgage-backed securities · Freddie Mac: its secondary-market role · Ginnie Mae 101: issuer and guarantor roles

      Report a problem with fin-6
    7. Question 7 · fin-7 · HECM benefits and continuing obligations

      A qualified 68-year-old obtains an FHA-insured loan against a paid-off principal residence. Monthly principal-and-interest payments are not required while the borrower meets occupancy, tax, insurance, maintenance, and other conditions. Which loan is described?

      1. A conventional home equity loan with scheduled monthly repayment
      2. A blanket development mortgage
      3. A wraparound purchase mortgage
      4. A Home Equity Conversion Mortgage (HECM)
      Show answer and explanation

      Answer D. A Home Equity Conversion Mortgage (HECM)

      The HECM is FHA’s insured reverse mortgage for eligible borrowers age 62 or older. It permits borrowing against home equity without required monthly principal-and-interest payments while applicable conditions are met. It is still a loan, and property charges and maintenance remain obligations. A non-borrowing spouse’s protection is conditional and differs from being a co-borrower.

      Remember: “No monthly principal-and-interest payment” is not “no bills” or “no repayment ever.”

      Why the other choices do not work
      • A. A conventional home equity loan with scheduled monthly repayment

        The stated absence of required monthly principal-and-interest payments points to the HECM structure, not this ordinary home equity loan.

      • B. A blanket development mortgage

        A blanket development loan covers multiple parcels, not the homeowner’s stated reverse mortgage.

      • C. A wraparound purchase mortgage

        A wraparound includes an existing mortgage in a new obligation; this home is paid off and the loan is FHA-insured equity conversion.

      Sources: HUD: FHA Home Equity Conversion Mortgages · CFPB: HECM age, equity, and counseling requirements · CFPB: reverse mortgage borrower responsibilities · CFPB: HECM co-borrowers and eligible non-borrowing spouses

      Report a problem with fin-7
    8. Question 8 · fin-8 · Discount points on the loan amount

      A lender charges 2 discount points on a $320,000 mortgage. How much do the points cost?

      1. $3,200
      2. $8,000
      3. $6,400
      4. $64,000
      Show answer and explanation

      Answer C. $6,400

      One point is 1% of the loan amount. Two points cost $320,000 × 0.02 = $6,400. The dollar cost does not tell you the exact interest-rate reduction. That depends on the lender’s pricing, the loan, and market conditions.

      Remember: Use the loan amount, not the purchase price. Two points do not mean a two-percentage-point rate reduction.

      Why the other choices do not work
      • A. $3,200

        $3,200 pays for one point on this loan.

      • B. $8,000

        $8,000 would equal 2.5% of this loan, not the stated 2%.

      • D. $64,000

        $64,000 is 20% of the loan. Convert 2% to 0.02, not 0.20.

      Sources: CFPB: discount points and lender credits

      Report a problem with fin-8
    9. Question 9 · fin-9 · Federal Reserve influence on mortgage pricing

      When the Federal Reserve raises its target range for the federal funds rate to tighten monetary policy, which statement is most accurate?

      1. It influences short-term rates and broader financial conditions, which can affect mortgage pricing and credit availability
      2. Every fixed mortgage rate must rise by exactly the same number of percentage points
      3. It directly replaces the interest rate in every existing fixed-rate mortgage
      4. Fannie Mae must stop buying mortgages
      Show answer and explanation

      Answer A. It influences short-term rates and broader financial conditions, which can affect mortgage pricing and credit availability

      The Fed influences short-term interest rates and financial conditions. Mortgage pricing also responds to longer-term market yields, expectations, risk, and loan characteristics. A policy change does not rewrite an existing fixed-rate note or force every new mortgage quote to move by the same amount.

      Remember: Influence is not a guaranteed one-for-one change. Do not confuse the federal funds rate with a borrower’s note rate.

      Why the other choices do not work
      • B. Every fixed mortgage rate must rise by exactly the same number of percentage points

        Mortgage rates do not mechanically track each federal funds change by an identical amount.

      • C. It directly replaces the interest rate in every existing fixed-rate mortgage

        An existing fixed-rate note keeps its contractual rate; a Fed decision does not replace it.

      • D. Fannie Mae must stop buying mortgages

        A target-rate change does not direct Fannie Mae to stop its secondary-market purchases.

      Sources: Federal Reserve: monetary policy · Fannie Mae: loan purchases and mortgage-backed securities

      Report a problem with fin-9

    Your next step toward exam day

    Get more practice before exam day.

    Keep preparing with 1,142 questions across all 19 areas. Review missed answers, work on weak topics, and take full-length timed exams in Pass Florida. Start with free access. The full package is $39.99 once, with no subscription.

    1,142 questionsMath CoachTrap Library$39.99 once

    Exam prep only. Not a substitute for the 63-hour course, DBPR steps, or Pearson VUE scheduling.

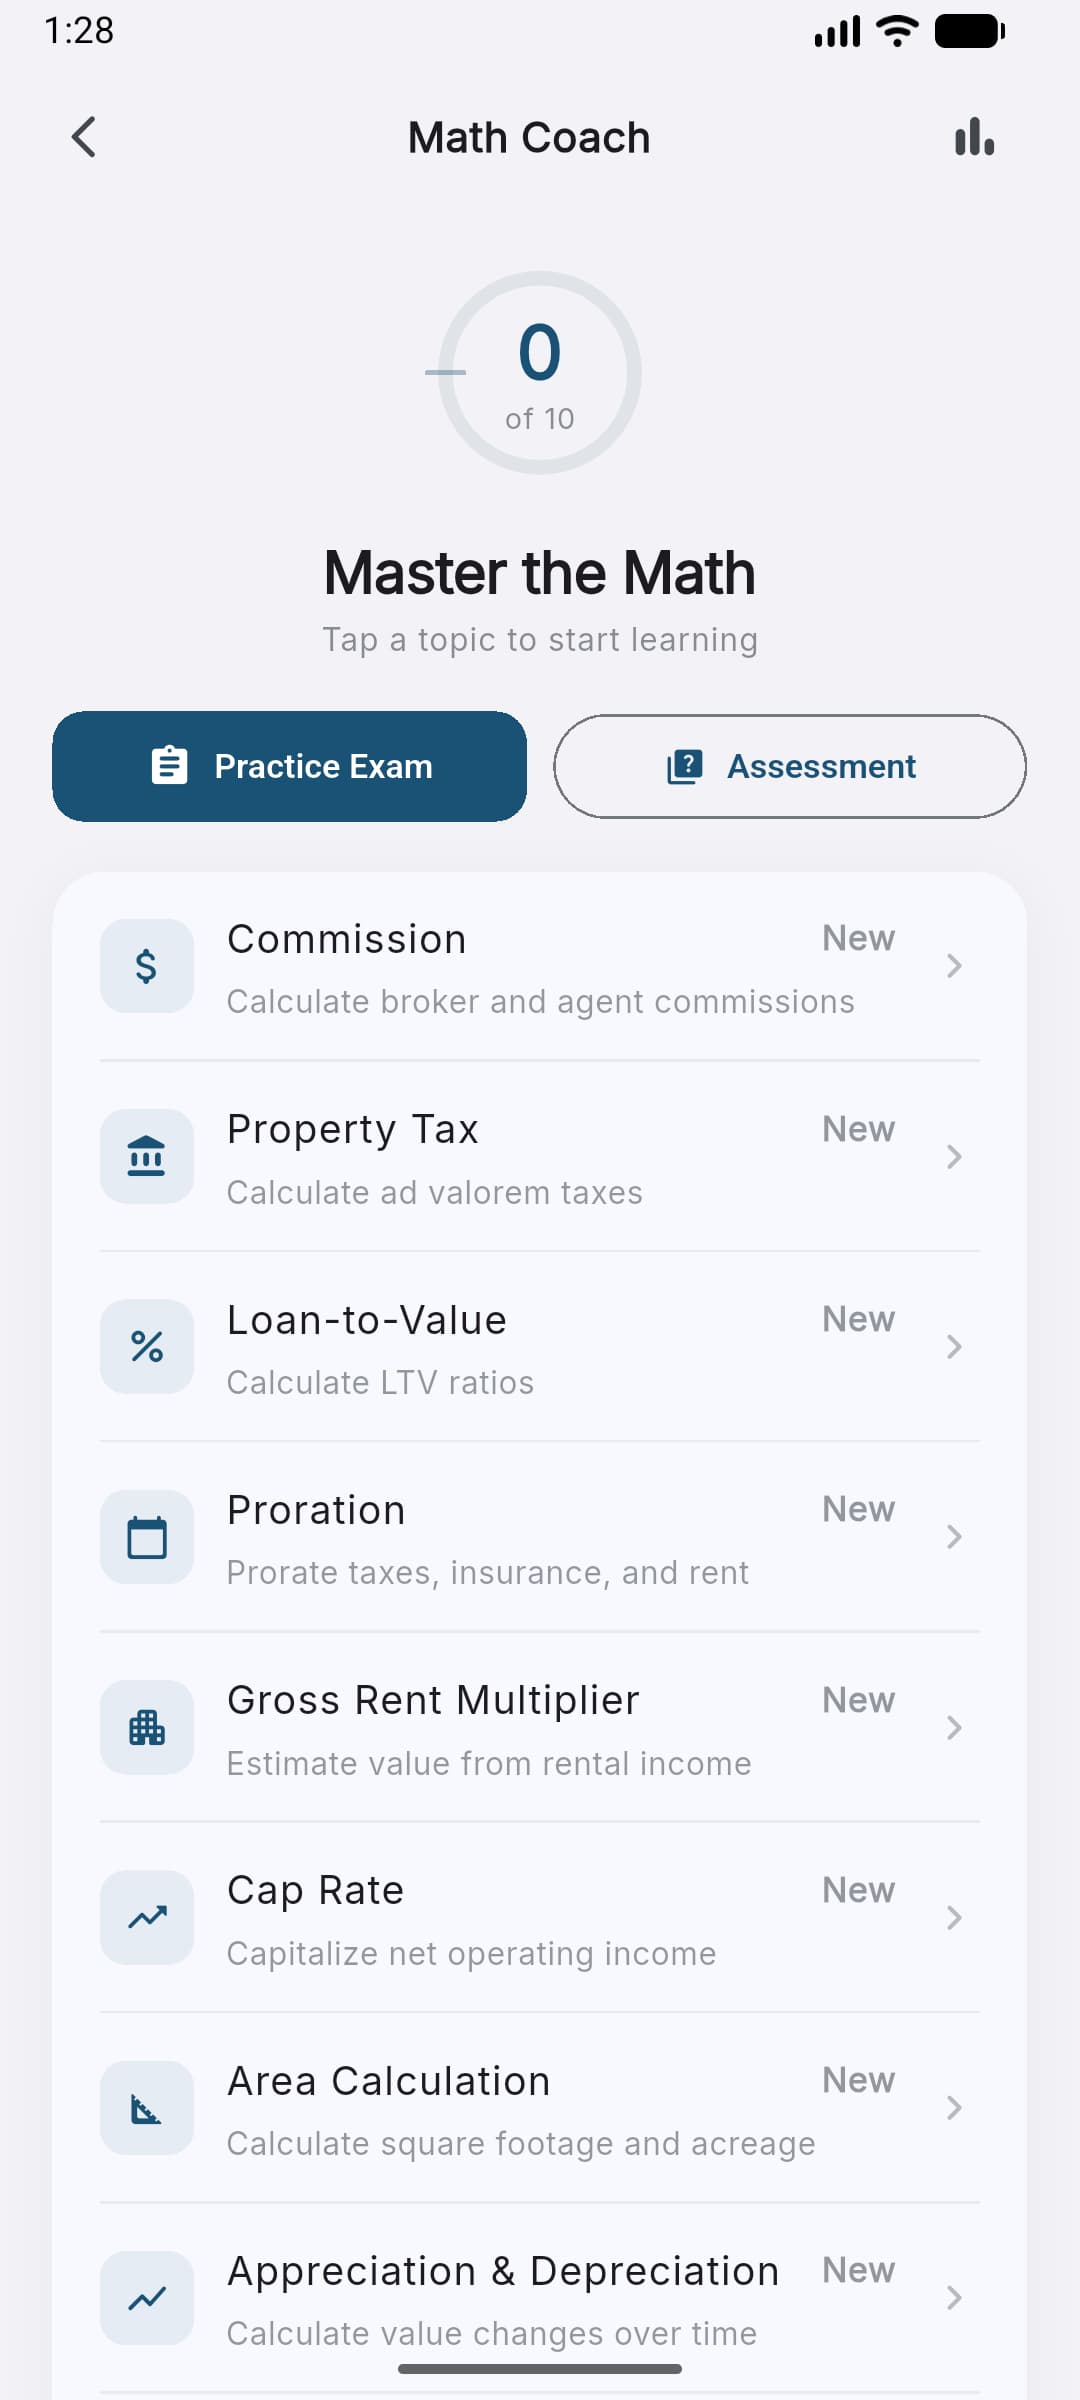
    Pass Florida Math Coach showing a worked real estate calculation
    Work through the math
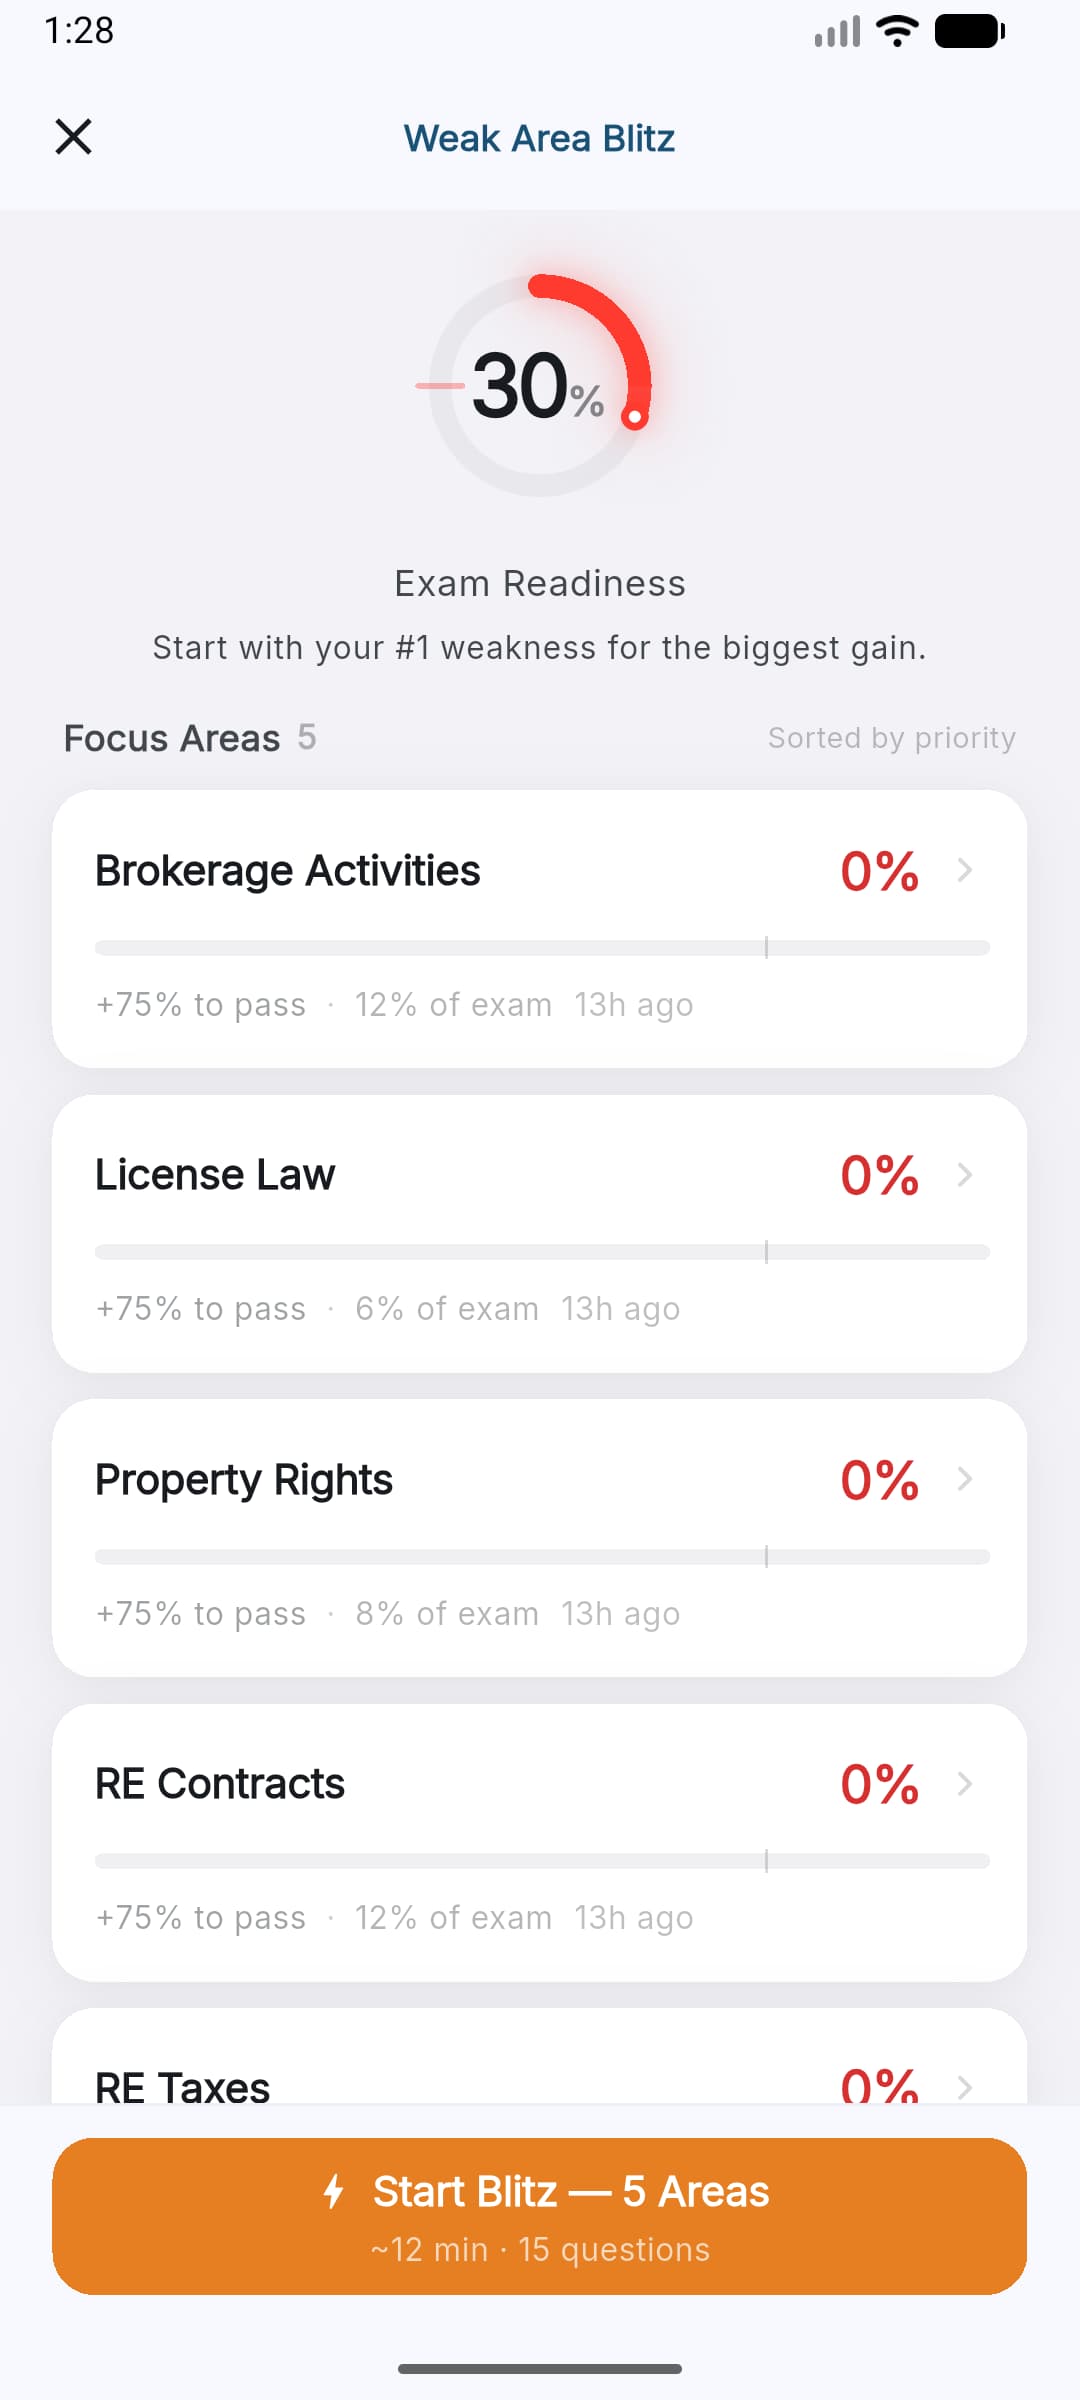
    Pass Florida app showing practice focused on weak areas
    Practice what needs work

    Study in your browser, or download for iPhone and Android. Offline study is available in the mobile app. Your free website quiz result does not transfer to the app.

    08 / Check the published outline

    Five exam headings, with a clear next step

    The candidate booklet gives this topic five headings. The course syllabus covers related mortgage structures in Sections 12 and 13. This resource draws those connections without treating nine questions as full mastery.

    A. The mortgage market and money supply

    In this resource: The market diagram, intermediation notes, and Question 9 explain how funds and rate influences reach lending.

    Also review: Review credit availability, intermediation, disintermediation, and the limits of simple cause-and-effect predictions about rates.

    B. Federal regulatory bodies

    In this resource: The institution comparison and reference notes distinguish the Fed, FHFA, FHA/HUD, and the secondary-market participants.

    Also review: Know each body's role. Do not classify every housing-finance participant as a regulator or confuse loan insurance with an MBS guaranty.

    C. Primary mortgage market

    In this resource: Question 5 identifies origination. Questions 1–4 and 7 add financing structures and HECM conditions.

    Also review: Review depository and nondepository lenders, mortgage brokers and originators, seller financing, and loan servicing.

    D. Secondary mortgage market

    In this resource: Questions 5–6, the market diagram, and the Ginnie Mae example distinguish loan origination, purchases, and securitization.

    Also review: Review conforming loans, portfolio lending, and the differences between Fannie Mae, Freddie Mac, and Ginnie Mae.

    E. Mortgage fees

    In this resource: Question 8, the points calculator, and two worked examples cover percentage fees and a simple break-even comparison.

    Also review: Separate discount points from origination fees and lender credits. A percentage charge does not automatically purchase a specified rate reduction.

    DBPR candidate booklet: Types of Mortgages and Sources of Financing, 4% supplies the 4% weight and five headings. FREC Course I syllabus: Sections 12 and 13 also calls for FHA and VA features, borrower qualification, mortgage fraud, and fair-credit and disclosure rules. Continue with the linked topics for those areas.

    A quick method for your next financing question

    First identify the activity. Creating a loan for a borrower is primary-market origination. Buying an existing loan or packaging loans into securities is secondary-market activity. Servicing the payments is a separate function.

    For loan types, identify the collateral and payment structure. Multiple parcels suggest a blanket mortgage; real and personal property suggest a package. A wraparound retains the underlying loan. Draws identify staged construction funding.

    For math, write down the base and the unit. Points use the loan amount. An ARM uses index plus margin subject to its caps. An amortization exercise subtracts interest from the principal-and-interest payment to find the principal reduction.

    Questions about mortgage types and financing

    Frequently asked questions

    How much of the Florida exam covers types of mortgages and financing?

    The published DBPR sales associate candidate booklet assigns this area 4%, about four questions on the 100-question exam. Its five headings are the mortgage market and money supply, federal regulatory bodies, primary market, secondary market, and mortgage fees. The Course I syllabus supplies additional detail and related loan structures.

    What is the difference between blanket and package mortgages?

    A blanket mortgage covers multiple parcels. A package mortgage includes real and personal property, such as separately identified movable furniture. A partial release clause in a blanket mortgage lets a specified parcel leave that lien when the agreed conditions are met; it does not erase every other lien.

    How does a wraparound mortgage work?

    A new, larger junior obligation includes the unpaid balance of an existing loan that remains in place. The buyer pays the wraparound lender, often the seller, who continues paying the underlying lender. The parties must address the original loan’s due-on-sale clause and payment arrangements; continuing payments alone does not establish lender consent.

    What is a construction takeout loan?

    It is permanent financing used to repay the construction loan. Construction funds are commonly advanced in draws as work progresses. A construction-to-permanent loan may instead convert under its agreed terms. Read the maturity and conversion provisions in the question rather than treating every construction loan as identical.

    What is the primary versus secondary mortgage market?

    The primary market is where lenders originate loans with borrowers. The secondary market involves existing loans and mortgage-backed securities. Selling a mortgage can replenish a lender’s funds for new lending. Some lenders keep loans in portfolio, and the loan’s owner and servicer may be different companies.

    What is the difference between Fannie Mae, Freddie Mac, and Ginnie Mae?

    Fannie Mae and Freddie Mac buy eligible mortgages from lenders and securitize many of them. They do not originate consumer home loans directly. Ginnie Mae guarantees timely principal and interest on qualifying MBS issued by approved issuers and backed by federally insured or guaranteed loans. It does not buy the mortgages or issue the securities itself.

    Does the Federal Reserve set mortgage rates?

    The Fed influences short-term rates and broader financial conditions, but it does not set each borrower’s mortgage quote. Mortgage rates also respond to longer-term market yields, expectations, risk, and loan characteristics. A Fed rate change does not rewrite an existing fixed-rate mortgage or require a matching change in every new mortgage rate.

    How much is one mortgage discount point?

    One point costs 1% of the loan amount. Two points on a $320,000 loan cost $6,400. Use the amount borrowed, not the purchase price. A point’s cost is defined, but the interest-rate reduction it buys is not a universal fixed amount.

    Are discount points the same as an origination fee?

    No. Discount points are paid for a lower interest rate relative to comparable zero-point pricing. An origination fee compensates the lender for originating the loan. Both can be expressed as a percentage, but their purpose differs. Read the fee label and the lender’s disclosures.

    How do I calculate the break-even period for mortgage points?

    For a simple comparison, divide the extra upfront points cost by constant monthly principal-and-interest savings. A $4,500 cost divided by $75 monthly savings equals 60 months. This shortcut leaves out tax effects, the time value of money, and loan-balance differences; compare otherwise comparable offers and the expected time you will keep the loan.

    How do index, margin, and caps work on an ARM?

    Add the index and the contractual margin, then apply the loan’s adjustment rules and caps. If index plus margin is 7.25% but the first-adjustment cap limits a 4.5% initial rate to a two-percentage-point increase, the rate cannot exceed 6.5% at that adjustment. Initial, subsequent, and lifetime caps can differ.

    Does a reverse mortgage eliminate taxes, insurance, or repayment?

    No. The FHA-insured HECM permits eligible borrowers age 62 or older to access home equity without required monthly principal-and-interest payments while applicable conditions are met. Taxes, insurance, maintenance, and other property charges remain obligations. The loan becomes due under its terms, such as after the last borrower’s death or a qualifying move-out event, subject to applicable protections.

    Can a non-borrowing spouse stay after a HECM borrower dies?

    Possibly, under the applicable HUD conditions. A qualifying eligible non-borrowing spouse may receive a deferral of repayment, but does not become a co-borrower or receive further loan advances. The loan’s date, spouse status, occupancy, documentation, and ongoing obligations matter. Protection is not automatic for every spouse or other person living in the home.

    Are these questions free, and where can I keep preparing?

    All nine questions, 27 wrong-choice explanations, six worked examples, and the points calculator are free without an account. Open the Pass Florida web app or download the mobile app for more practice, missed-answer review, weak-area practice, and full-length timed exams across all 19 areas. These are original practice questions, not actual or recalled Pearson VUE items.

    Sources and editorial review

    Check the reasoning behind the answer.

    Published by Pass Florida. Reviewed on for material applicable through .

    This review checked the questions, examples, and calculator against the published DBPR outline, FREC Course I syllabus, CFPB and HUD guidance, Federal Reserve and FHFA references, the institutions' own descriptions, and the cited federal due-on-sale statute.

    The 4% weight comes from the January 2025 candidate booklet. The published Course I syllabus is effective January 1, 2023. The page distinguishes that exam outline from related course material and explains program conditions without presenting hypothetical rates as September 2026 offers.

    Found an error? Use the correction link under a question or send the question ID and supporting source.

    1. DBPR candidate booklet: Types of Mortgages and Sources of Financing, 4%
    2. FREC Course I syllabus: Sections 12 and 13
    3. Fannie Mae: loan purchases and mortgage-backed securities
    4. Freddie Mac: its secondary-market role
    5. Ginnie Mae 101: issuer and guarantor roles
    6. Federal Reserve: monetary policy
    7. Federal Reserve: reserve requirements
    8. FHFA: supervision and housing-finance responsibilities
    9. CFPB: discount points and lender credits
    10. HUD: FHA Home Equity Conversion Mortgages
    11. CFPB: HECM age, equity, and counseling requirements
    12. CFPB: reverse mortgage borrower responsibilities
    13. CFPB: HECM co-borrowers and eligible non-borrowing spouses
    14. 12 U.S.C. 1701j-3: due-on-sale clauses and exceptions
    15. CFPB: ARM index and margin
    16. CFPB: initial, subsequent, and lifetime ARM caps
    17. CFPB: how mortgage amortization works
    18. CFPB: negative amortization
    19. CFPB: loan sales and servicing transfers

    Key terms for types of mortgages and financing

    Review a definition, worked example, or common exam trap before your next quiz.